
Telecommunications and media company Comcast (NASDAQ:CMCSA) met Wall Street’s revenue expectations in Q3 2026, but sales were flat year on year at $29.3 billion. Its non-GAAP profit of $1.07 per share was 8.6% above analysts’ consensus estimates.
Is now the time to buy Comcast? Find out by accessing our full research report, it’s free.
Comcast (CMCSA) Q3 2026 highlights:
- Revenue: $29.3 billion vs analyst estimates of $29.23 billion (flat year on year, in line)
- Adjusted EPS: $1.07 vs analyst estimates of $0.98 (8.6% beat)
- Adjusted EBITDA: $9.11 billion vs analyst estimates of $8.88 billion (31.1% margin, 2.5% beat)
- Operating Margin: 18.2%, up from 16.8% in the same quarter last year
- Free Cash Flow Margin: 14.4%, similar to the same quarter last year
- Domestic Broadband Customers: down 3.09 million year on year
- Market Capitalization: $78.35 billion
Company overview
Formerly known as American Cable Systems, Comcast (NASDAQ:CMCSA) is a multinational telecommunications company offering a wide range of services.
Revenue growth
Reviewing a company’s long-term sales performance reveals insights into its quality. Even a bad business can shine for one or two quarters, but a top-tier one grows for years. Regrettably, Comcast’s sales grew at a weak 1.1% compounded annual growth rate over the last five years. This fell short of our benchmarks and is a tough starting point for our analysis.
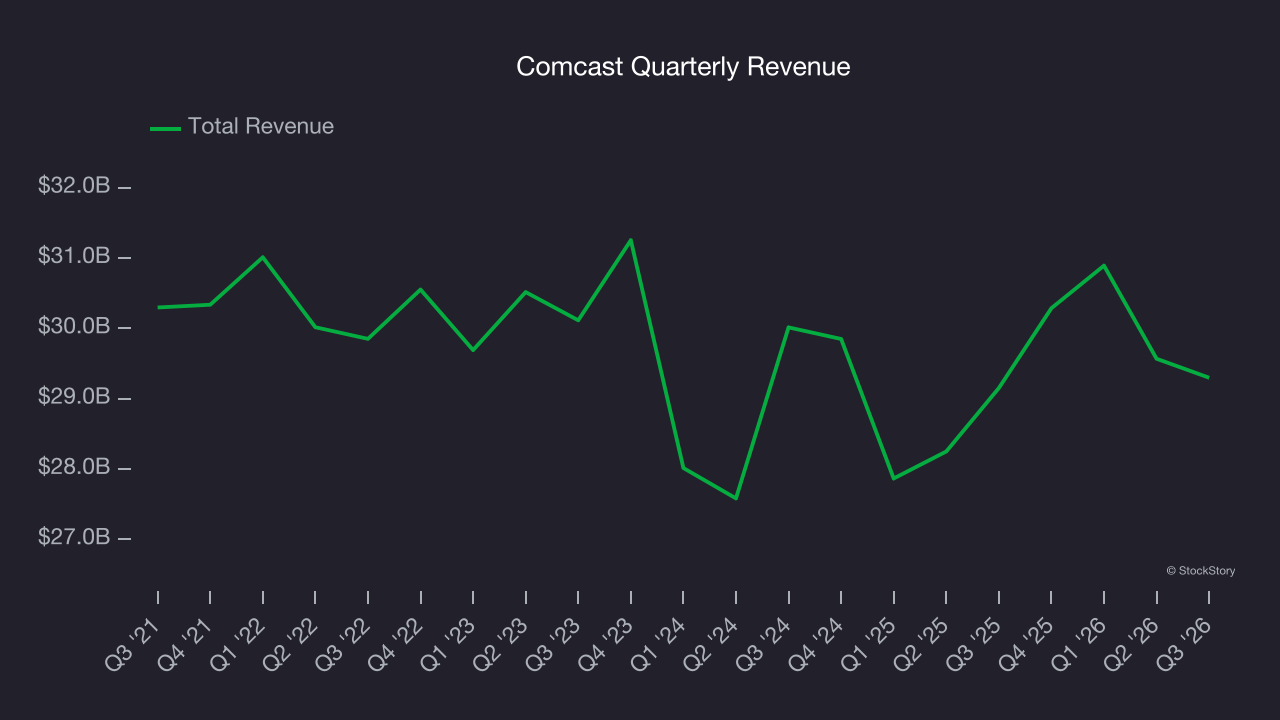
We at StockStory place the most emphasis on long-term growth, but within consumer discretionary, a stretched historical view may miss a company riding a successful new product or trend. Comcast’s annualized revenue growth of 1.4% over the last two years aligns with its five-year trend, suggesting its demand was consistently weak. 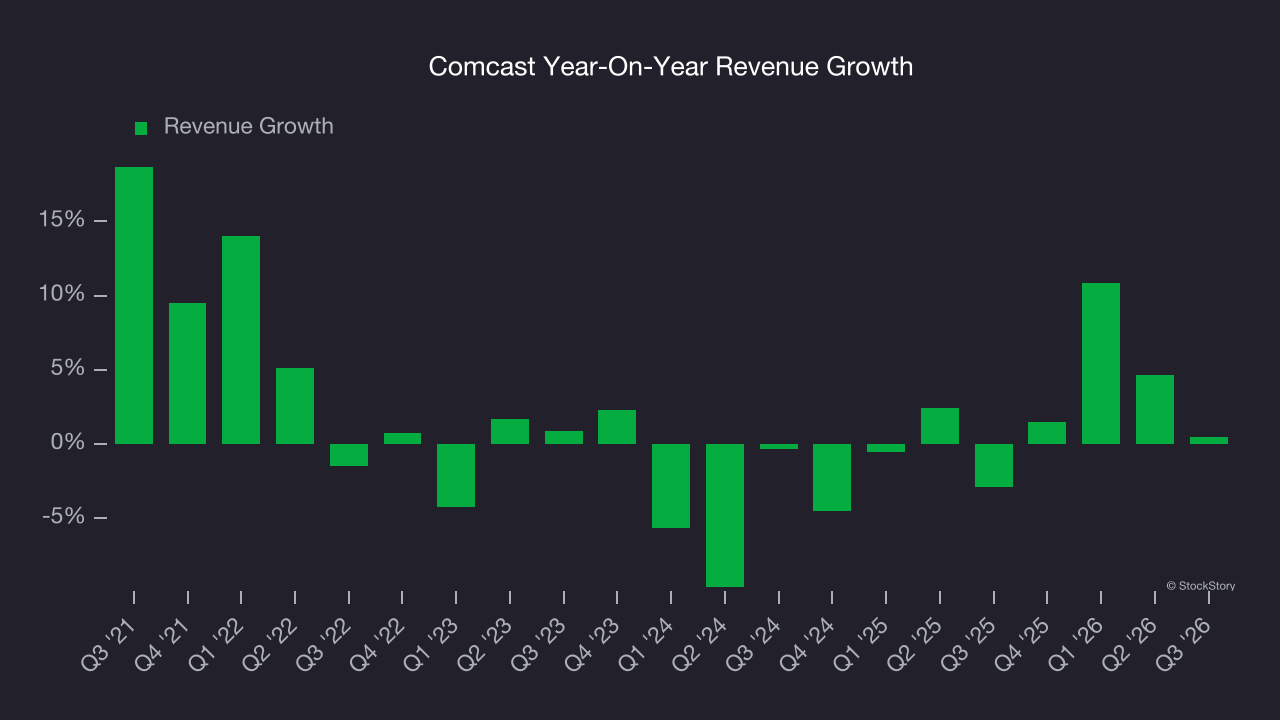
We can better understand the company’s revenue dynamics by analyzing its number of domestic broadband customers and domestic video customers, which clocked in at 28.34 million and 10.39 million in the latest quarter. Over the last two years, Comcast’s domestic broadband customers averaged 5.6% year-on-year declines while its domestic video customers averaged 10.3% year-on-year declines. 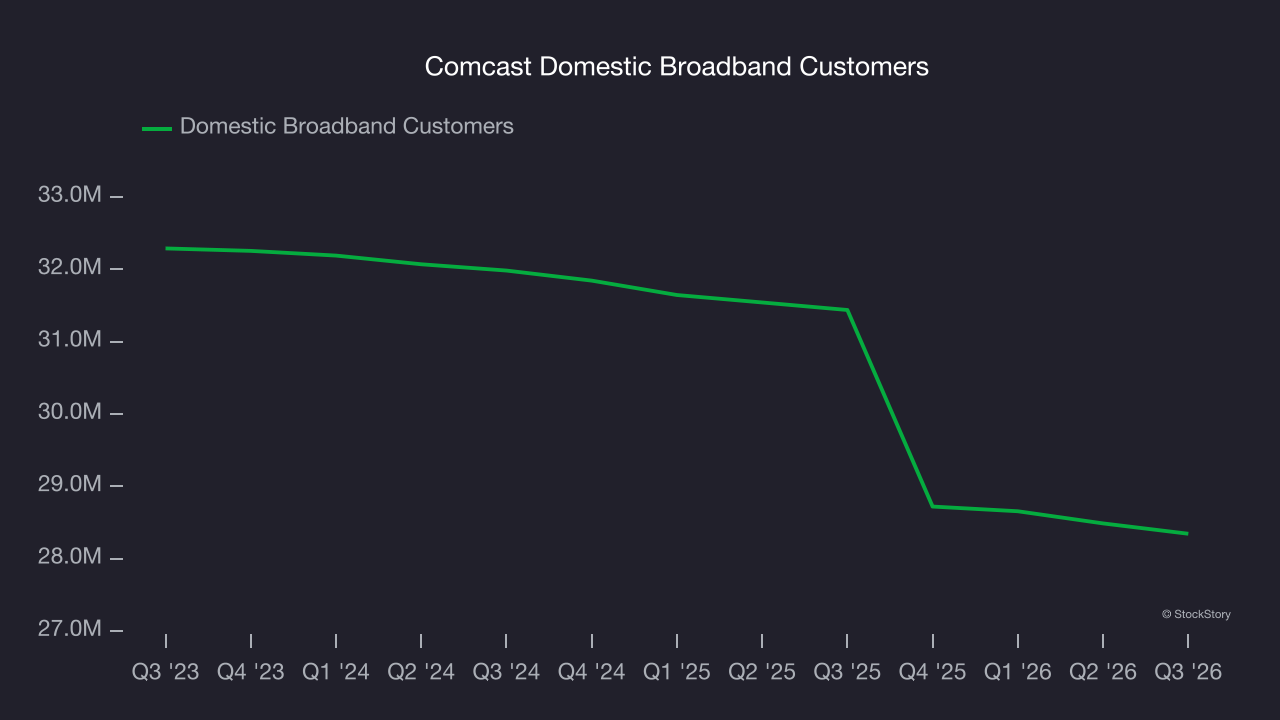
This quarter, Comcast’s $29.3 billion of revenue was flat year on year and in line with Wall Street’s estimates.
Looking ahead, sell-side analysts expect revenue to decline by 2.3% over the next 12 months, a deceleration versus the last two years. This projection is underwhelming and suggests its products and services will see some demand headwinds.
ONE MORE THING: 3 Hidden Platforms Growing 3X Faster than Amazon, Google, and PayPal. Amazon, Google, and Meta all followed the same playbook: Dominate an ignored market. Build an unbeatable moat. Scale until you’re unstoppable.
These three platforms are running that exact playbook right now. The early investors in Amazon made fortunes. The early investors in these could do the same. Get All 3 Stocks Here for FREE.
Operating margin
Comcast’s operating margin has shrunk over the last 12 months and averaged 15.9% over the last two years. The company’s profitability was mediocre for a consumer discretionary business and shows it couldn’t pass its higher operating expenses onto its customers.
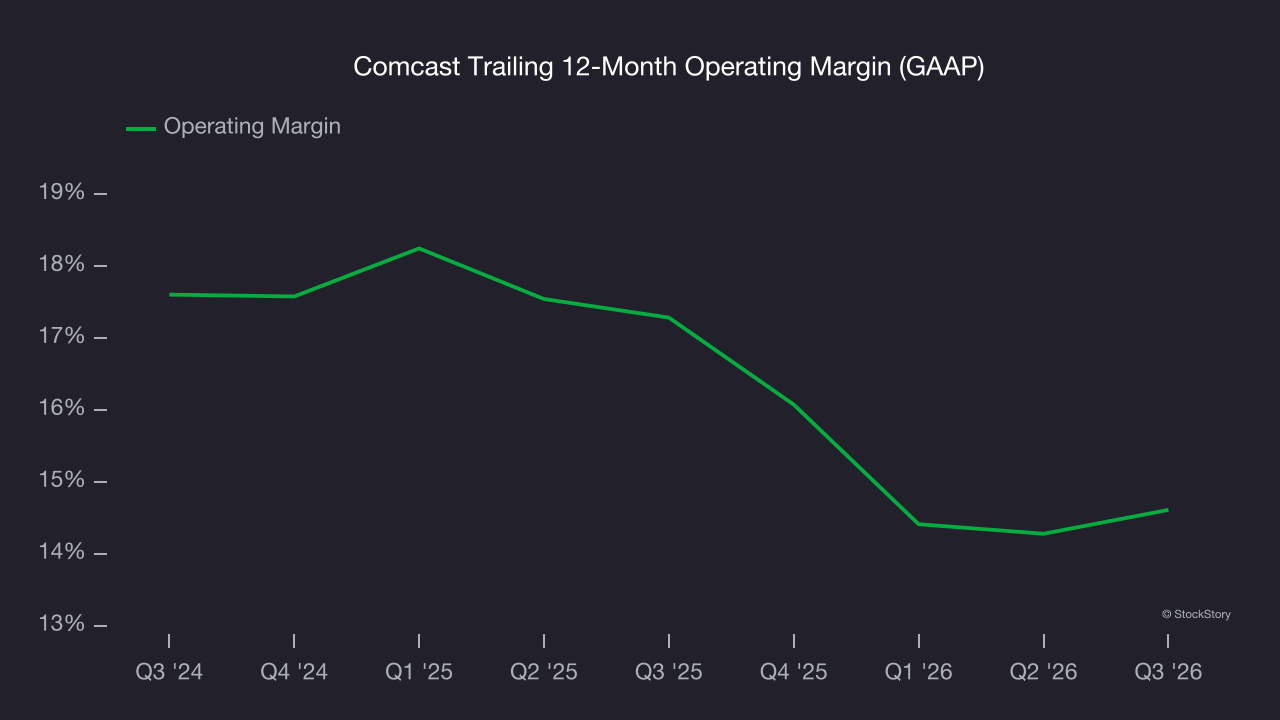
In Q3, Comcast generated an operating margin profit margin of 18.2%, up 1.3 percentage points year on year. This increase was a welcome development and shows it was more efficient.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth — for example, a company could inflate its sales through excessive spending on advertising and promotions.
Comcast’s EPS grew at 4.3% compounded annual growth rate over the last five years. This performance was better than its revenue growth but doesn’t tell us much about its business quality because its operating margin improvement was less than peers.
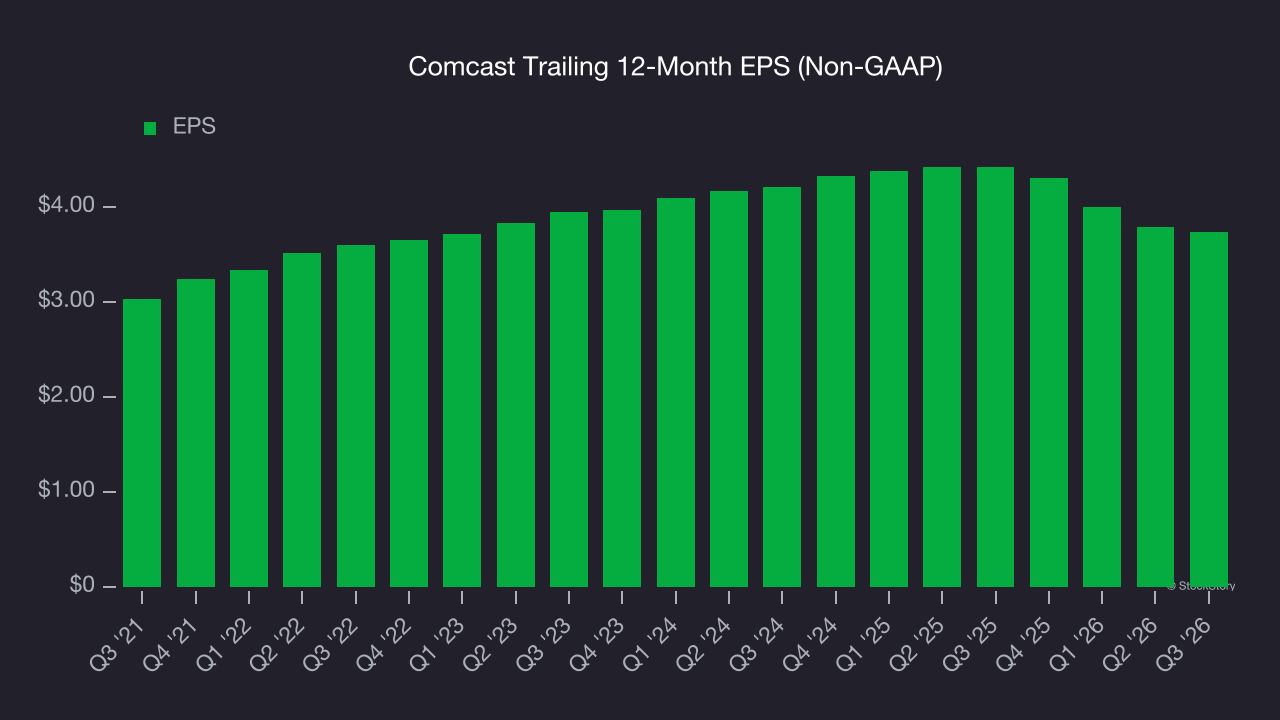
In Q3, Comcast reported adjusted EPS of $1.07, down from $1.12 in the same quarter last year. Despite falling year on year, this print beat analysts’ estimates by 8.5%. Over the next 12 months, Wall Street expects Comcast’s full-year EPS to shrink by 4.7% from $3.74 to $3.57.
Key takeaways from Comcast’s Q3 results
It was good to see Comcast beat analysts’ EPS expectations this quarter. We were also happy its EBITDA outperformed Wall Street’s estimates. Overall, this print had some key positives. The stock traded up 1.1% to $22.33 immediately after reporting.
So do we think Comcast is an attractive buy at the current price? When making that decision, it’s important to consider its valuation, business qualities, as well as what has happened in the latest quarter. We cover that in our actionable full research report which you can read here (it’s free).