
Rural goods retailer Tractor Supply (NASDAQ:TSCO) reported revenue ahead of Wall Street’s expectations in Q3 2026, with sales up 5.1% year on year to $3.91 billion. Its GAAP profit of $0.43 per share was 6.1% above analysts’ consensus estimates.
Is now the time to buy Tractor Supply? Find out by accessing our full research report, it’s free.
Tractor Supply (TSCO) Q3 2026 highlights:
- Revenue: $3.91 billion vs analyst estimates of $3.82 billion (5.1% year-on-year growth, 2.4% beat)
- EPS (GAAP): $0.43 vs analyst estimates of $0.41 (6.1% beat)
- EPS (GAAP) guidance for the full year is $1.83 at the midpoint, roughly in line with what analysts were expecting
- Operating Margin: 7.9%, down from 9.2% in the same quarter last year
- Free Cash Flow Margin: 0%, similar to the same quarter last year
- Locations: 2,621 at quarter end, up from 2,570 in the same quarter last year
- Same-Store Sales were flat year on year (3.9% in the same quarter last year)
- Market Capitalization: $17.03 billion
“Our third quarter marked a step forward for Tractor Supply, with improved sales momentum and broader strength across our business. The actions we are taking around value, pet, digital and convenience gained traction in the quarter. I want to thank our more than 54,000 Team Members for their dedication to serving our customers every day. We are moving with urgency to sharpen our strategic priorities, drive productivity and make deliberate choices about where we invest our capital and resources. These efforts are designed to accelerate comparable store sales growth, restore operating margins and deliver attractive long-term shareholder returns. Our progress in the quarter and the actions underway give us confidence in our ability to deliver within our full-year guidance, which we are reaffirming today. As we head into the fourth quarter, our focus remains on being the dependable supplier our customers count on throughout the winter season,” said Hal Lawton, President and Chief Executive Officer of Tractor Supply.
Company overview
Started as a mail-order tractor parts business, Tractor Supply (NASDAQ:TSCO) is a retailer of general goods such as agricultural supplies, hardware, and pet food for the rural consumer.
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can put up a good quarter or two, but the best consistently grow over the long haul.
With $15.94 billion in revenue over the past 12 months, Tractor Supply is one of the larger companies in the consumer retail industry and benefits from a well-known brand that influences purchasing decisions. However, its scale is a double-edged sword because there are only a finite number of places to build new stores, making it harder to find incremental growth. For Tractor Supply to boost its sales, it likely needs to adjust its prices or lean into foreign markets.
As you can see below, Tractor Supply grew its sales at a sluggish 2.3% compounded annual growth rate over the last three years.
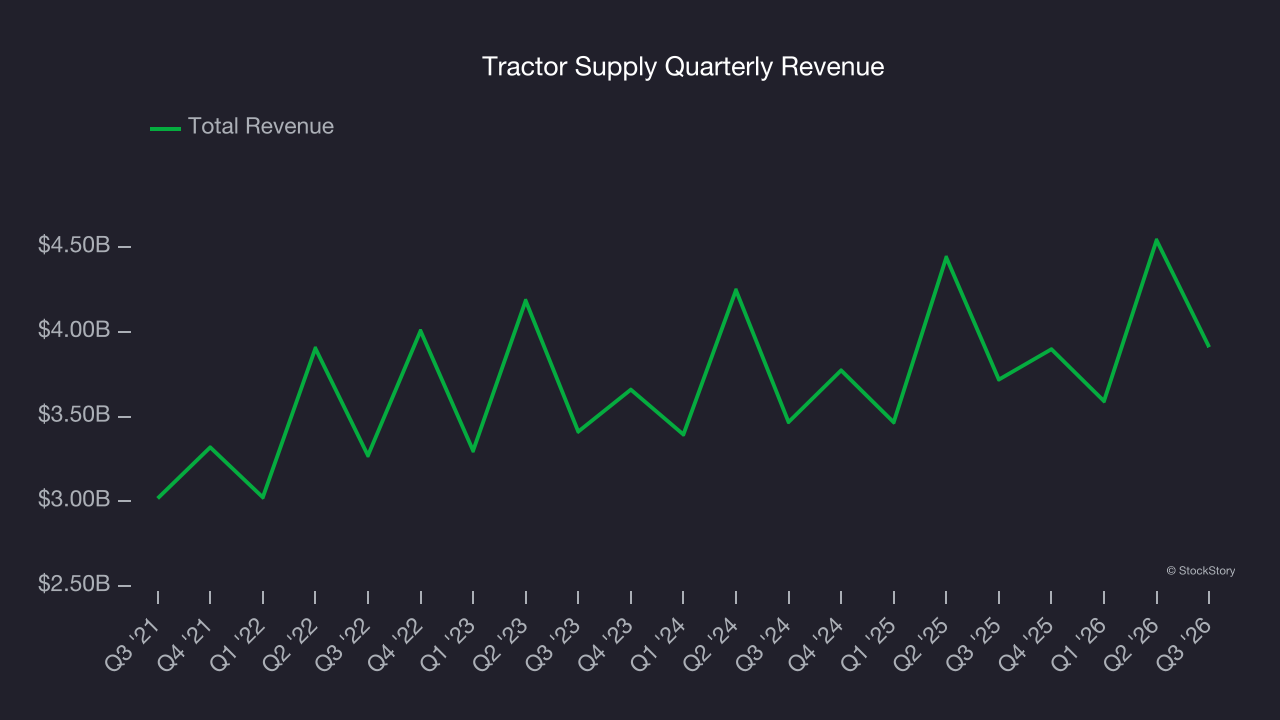
This quarter, Tractor Supply reported year-on-year revenue growth of 5.1%, and its $3.91 billion of revenue exceeded Wall Street’s estimates by 2.4%.
Looking ahead, sell-side analysts expect revenue to grow 3.1% over the next 12 months, similar to its three-year rate. This projection is above the sector average and implies its newer products will help support its historical top-line performance.
ALSO WORTH WATCHING: Nvidia’s Quiet Partner. Nvidia’s chips cost a hundred grand. The connectors that make them work cost even more. One company makes them all.
Every AI server needs specialized infrastructure the chip companies don’t make. High-speed cables. Power connectors. Thermal sensors. This 90-year-old company built a monopoly on it. The AI boom just started. This stock is still flying under the radar. Claim The Stock Ticker Here for FREE.
Store performance
Number of stores
The number of stores a retailer operates is a critical driver of how quickly company-level sales can grow.
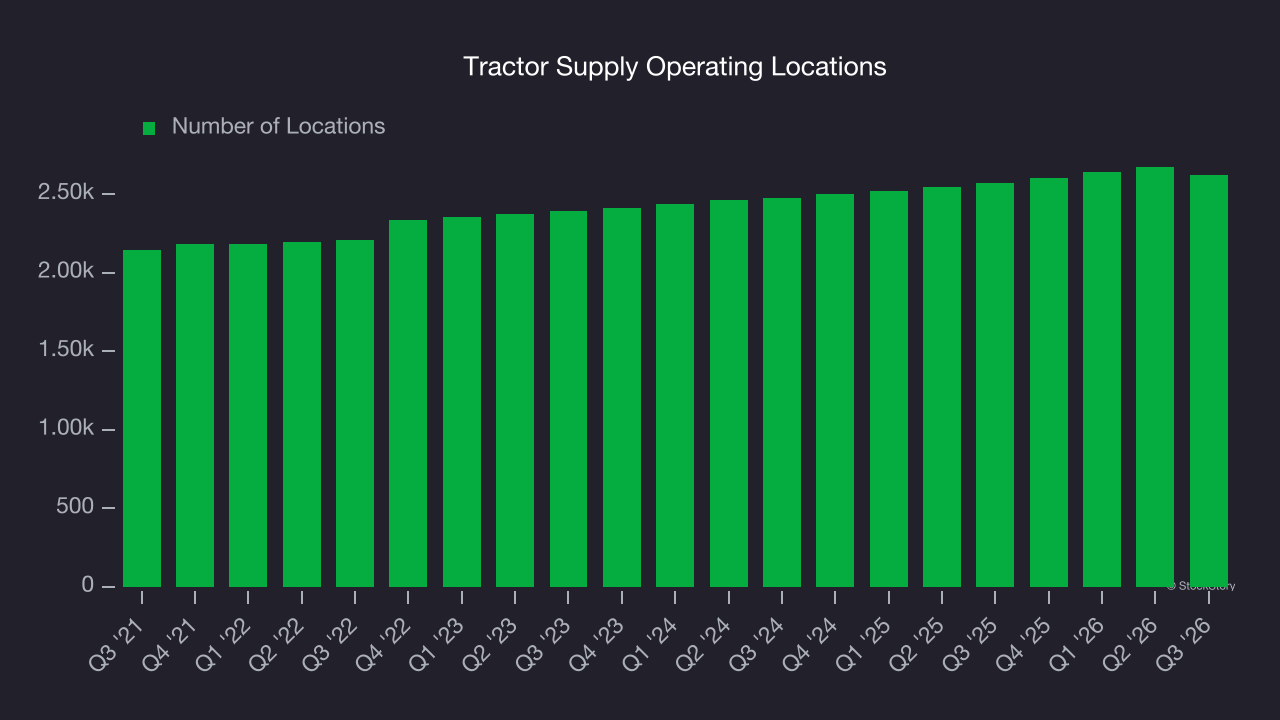
Tractor Supply operated 2,621 locations in the latest quarter. It has opened new stores quickly over the last two years, averaging 3.8% annual growth, faster than the broader consumer retail sector.
When a retailer opens new stores, it usually means it’s investing for growth because demand is greater than supply, especially in areas where consumers may not have a store within reasonable driving distance.
Same-store sales
A company’s store base only paints one part of the picture. When demand is high, it makes sense to open more. But when demand is low, it’s prudent to close some locations and use the money in other ways. Same-store sales provides a deeper understanding of this issue because it measures organic growth at brick-and-mortar shops for at least a year.
Tractor Supply’s demand within its existing locations has barely increased over the last two years as its same-store sales were flat. Tractor Supply should consider improving its foot traffic and efficiency before expanding its store base.
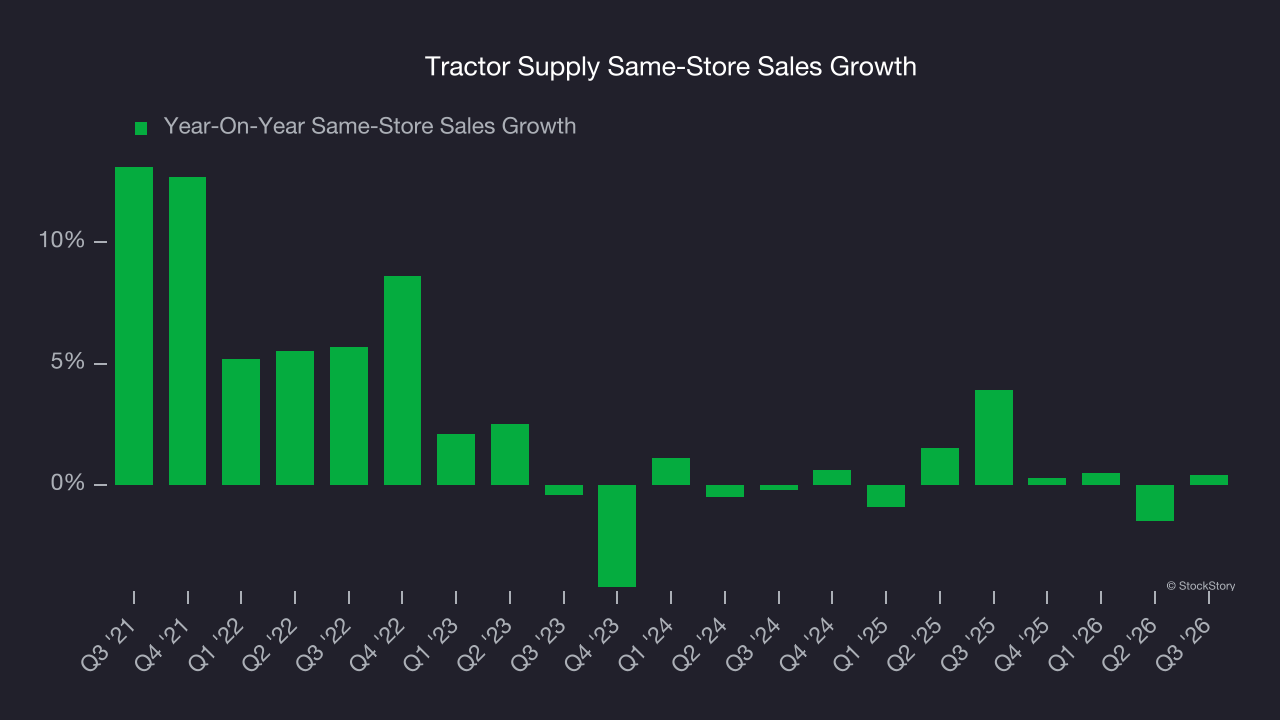
In the latest quarter, Tractor Supply’s year on year same-store sales were flat. This performance was more or less in line with its historical levels.
Key takeaways from Tractor Supply’s Q3 results
We enjoyed seeing Tractor Supply beat analysts’ revenue expectations this quarter. We were also glad its EPS outperformed Wall Street’s estimates. On the other hand, its gross margin slightly missed. Overall, this print had some key positives. The market seemed to be hoping for more, and the stock traded down 2% to $31.93 immediately after reporting.
Is Tractor Supply an attractive investment opportunity at the current price? What happened in the latest quarter matters, but not as much as longer-term business quality and valuation, when deciding whether to invest in this stock. We cover that in our actionable full research report which you can read here (it’s free).