
Food and beverage company PepsiCo (NASDAQ:PEP) announced better-than-expected revenue in Q3 2026, with sales up 5.6% year on year to $25.27 billion. Its non-GAAP profit of $2.34 per share was 1.9% above analysts’ consensus estimates.
Is now the time to buy PepsiCo? Find out by accessing our full research report, it’s free.
PepsiCo (PEP) Q3 2026 Highlights:
- Revenue: $25.27 billion vs analyst estimates of $24.96 billion (5.6% year-on-year growth, 1.3% beat)
- Adjusted EPS: $2.34 vs analyst estimates of $2.30 (1.9% beat)
- Operating Margin: 16.9%, up from 14.9% in the same quarter last year
- Free Cash Flow Margin: 18.5%, up from 15% in the same quarter last year
- Organic Revenue rose 3.1% year on year (beat)
- Sales Volumes were flat year on year (-3% in the same quarter last year)
- Market Capitalization: $168.9 billion
Company Overview
With a history that goes back more than a century, PepsiCo (NASDAQ:PEP) is a household name in food and beverages today and best known for its flagship soda.
Revenue Growth
A company’s long-term sales performance is one signal of its overall quality. Any business can put up a good quarter or two, but many enduring ones grow for years.
With $98.24 billion in revenue over the past 12 months, PepsiCo is one of the most widely recognized consumer staples companies. Its influence over consumers gives it negotiating leverage with distributors, enabling it to pick and choose where it sells its products (a luxury many don’t have). However, its scale is a double-edged sword because there are only a finite number of major retail partners, placing a ceiling on its growth. To accelerate sales, PepsiCo likely needs to optimize its pricing or lean into new products and international expansion.
As you can see below, PepsiCo’s 2.4% annualized revenue growth over the last three years was sluggish as consumers bought less of its products. We’ll explore what this means in the “Volume Growth” section.
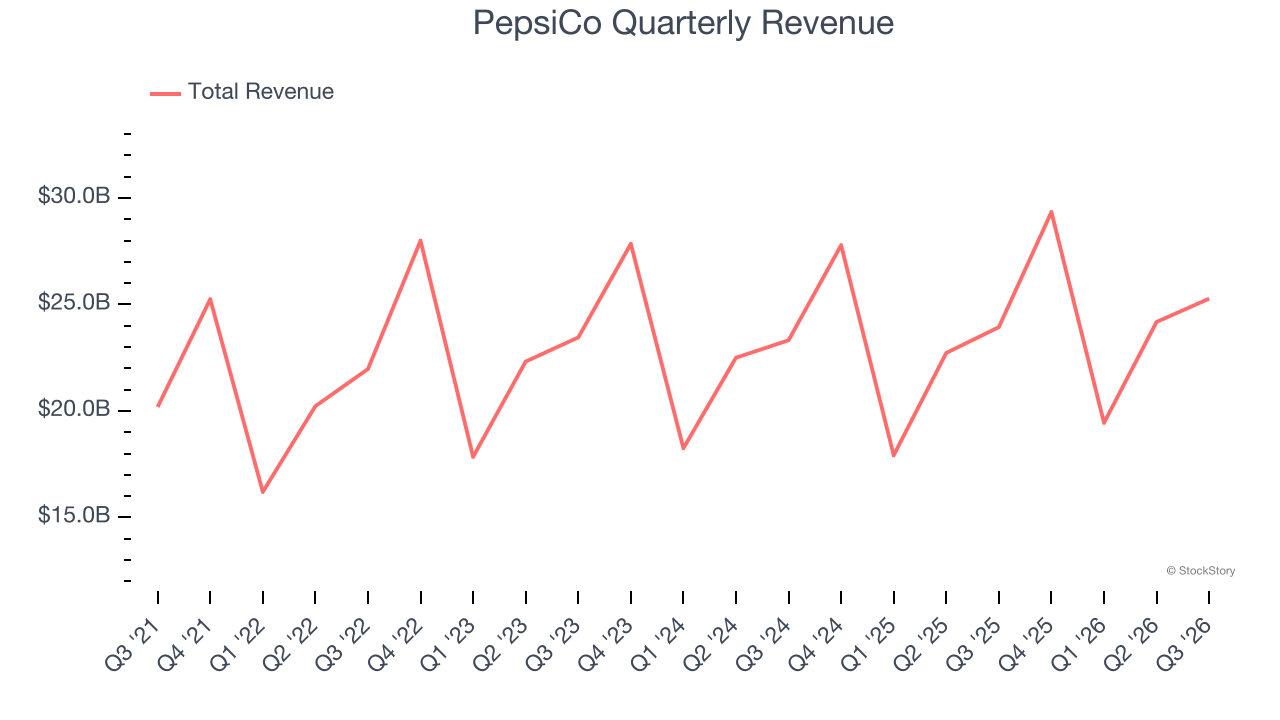
This quarter, PepsiCo reported year-on-year revenue growth of 5.6%, and its $25.27 billion of revenue exceeded Wall Street’s estimates by 1.3%.
Looking ahead, sell-side analysts expect revenue to grow 2.5% over the next 12 months, similar to its three-year rate. This projection is underwhelming and implies its newer products will not catalyze better top-line performance yet.
WHILE YOU’RE HERE: The Next Palantir? One satellite company captures images of every point on Earth. Every single day. The Pentagon wants it. Hedge funds are using it to beat earnings. You’ve probably never heard of it.
This is what the early days of Palantir looked like before it became a giant. Same playbook. Different technology. If you missed Palantir, you need to see this. Claim The Stock Ticker for Free HERE.
Volume Growth
Revenue growth can be broken down into changes in price and volume (the number of units sold). While both are important, volume is the lifeblood of a successful staples business as there’s a ceiling to what consumers will pay for everyday goods; they can always trade down to non-branded products if the branded versions are too expensive.
To analyze whether PepsiCo generated its growth from changes in price or volume, we can compare its volume growth to its organic revenue growth, which excludes non-fundamental impacts on company financials like mergers and currency fluctuations.
Over the last two years, PepsiCo’s average quarterly sales volumes have shrunk by 1%. This decrease isn’t ideal as the quantity demanded for consumer staples products is typically stable. Luckily, PepsiCo was able to offset fewer customers purchasing its products by charging higher prices, enabling it to generate 2.1% average organic revenue growth. We hope the company can grow its volumes soon, however, as consistent price increases (on top of inflation) aren’t sustainable over the long term unless the business is really, really special.
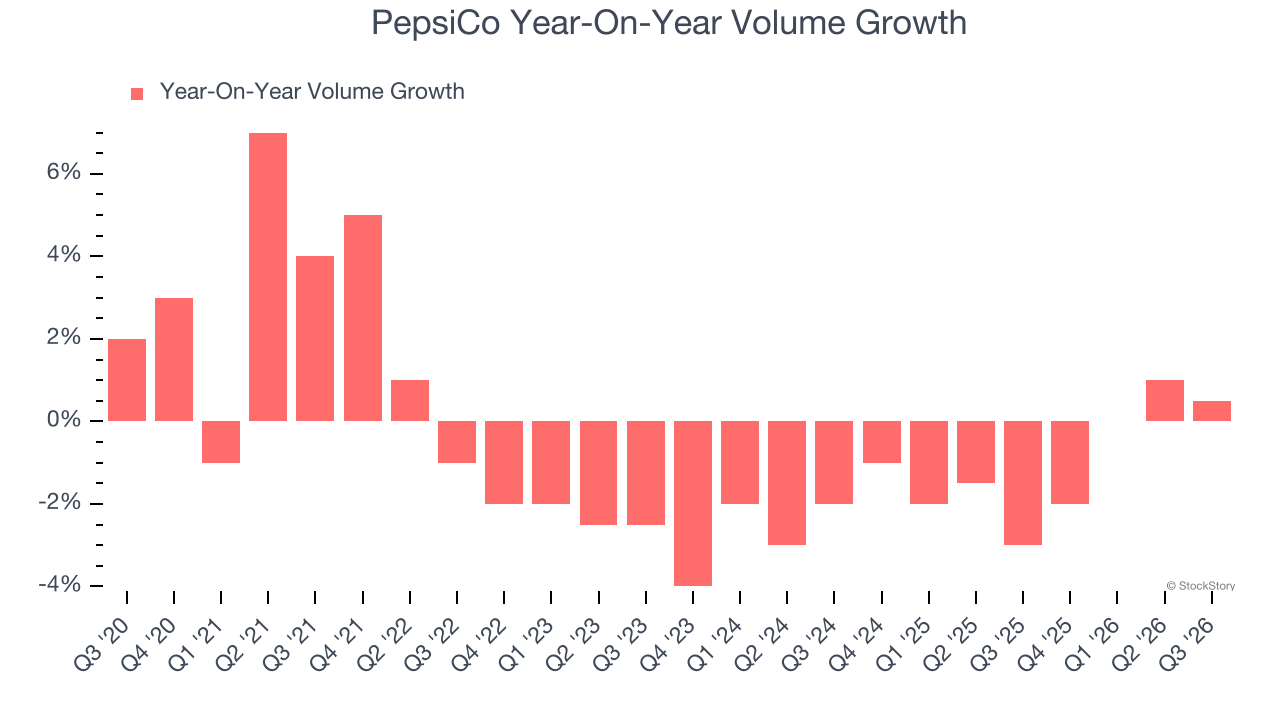
In PepsiCo’s Q3 2026, year on year sales volumes were flat. This result was a well-appreciated turnaround from its historical levels, showing the company is heading in the right direction.
Key Takeaways from PepsiCo’s Q3 Results
It was good to see PepsiCo narrowly top analysts’ revenue expectations this quarter. We were also happy its gross margin outperformed Wall Street’s estimates. Overall, this print had some key positives. The stock remained flat at $124.74 immediately following the results.
So should you invest in PepsiCo right now? What happened in the latest quarter matters, but not as much as longer-term business quality and valuation, when deciding whether to invest in this stock. We cover that in our actionable full research report which you can read here (it’s free).